Inaccurate Vehicle Details
The wrong trim, missing factory options, incorrect mileage or unsupported condition deductions can pull down the insurer’s number. We review the VIN, equipment and pre-loss condition against the valuation report.
PRIMUS · VEHICLE CLAIMS
A total loss shouldn’t mean settling for less.
Insurance companies routinely undervalue total loss settlements. We appraise your vehicle’s Actual Cash Value using local market evidence—not just the carrier’s first number.
Free initial evaluation · No obligation
Total Loss
Beyond the insurer’s valuation
Actual Cash Value (ACV) generally reflects what your vehicle was worth immediately before the loss, accounting for age, mileage and condition. It is not automatically the price of a new replacement or the balance on your loan. An inaccurate valuation can leave a substantial gap in your settlement.
The wrong trim, missing factory options, incorrect mileage or unsupported condition deductions can pull down the insurer’s number. We review the VIN, equipment and pre-loss condition against the valuation report.
Distant vehicles, mismatched equipment and unexplained adjustments may not represent what comparable vehicles cost locally. We examine the insurer’s selections and seek relevant local market comps.
Condition adjustments, fees and settlement deductions deserve documentation. Applicable taxes, title fees, deductibles and owner-retained salvage depend on state law and coverage; we review how they affect your offer.
A vehicle-specific ACV appraisal
We review your VIN, year, make, model, trim, mileage, options and documented pre-accident condition. Photos, maintenance records and the carrier’s report help establish the starting point.
We research comparable vehicles in your local market, considering available listings, dealer information and sales evidence where available. Asking prices are not assumed to equal final sale prices.
We account for meaningful differences in mileage, equipment and condition, prepare a supported ACV appraisal and present valuation discrepancies to the carrier within our authorized scope.
Appraisal rights and dispute options vary by policy, jurisdiction and whether you claim against your own insurer or another party’s carrier. Service availability depends on licensing and claim circumstances; no increase is guaranteed.
Real claims. Meaningful recoveries.
Behind every settlement is a vehicle owner who deserves a properly supported claim. Client identities remain confidential.
$65,541.66
Recovered settlement
Plus$1,267.30 for personal items left in the vehicle that required replacement.
$16,294.36 above the initial valuation
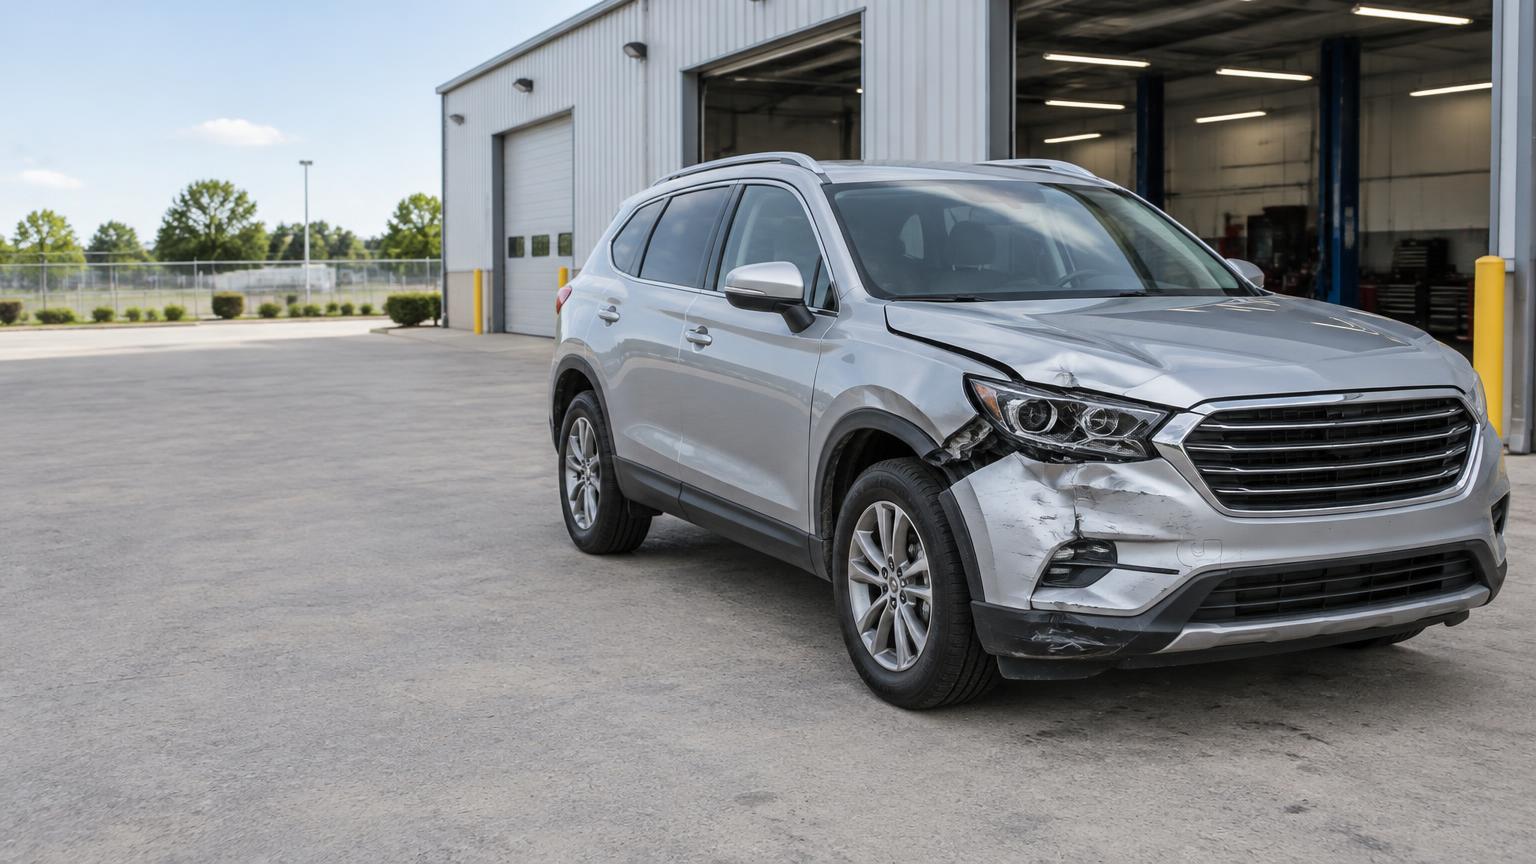
Challenged AAA’s low initial total loss valuation after an accident and recovered a substantially higher settlement for an anonymous SUV owner.
$5,792.00
Reported total resolution
Secured a resolution after the vehicle owner faced pushback on the repair settlement.
Reported figures are shown as supplied; the component amounts differ from the reported total by $0.47.
Thousands recovered
Across complex vehicle claims
Successfully challenged low insurance payouts, recovering thousands in hidden vehicle market devaluation and underpaid repair costs on complex commercial and passenger vehicle claims.
Past results do not guarantee a similar outcome. Every claim depends on its evidence, coverage and applicable law. Amounts shown in USD.
View success storiesA little clarity
You can request the complete valuation report and question factual errors or unsupported adjustments. Review deadlines, payment terms and any release before accepting a final settlement.
Your VIN, mileage, vehicle options, pre-loss photos, accident date, carrier valuation report, settlement offer and insurance policy. Local comparable listings and maintenance records can also help.
Some policies provide an appraisal process for valuation disputes, but the terms and availability vary. We review your policy and circumstances; legal disputes may require an attorney.
Start with a free evaluation of your total loss offer. Already a client? Head to your portal.