Damage the First Estimate Misses
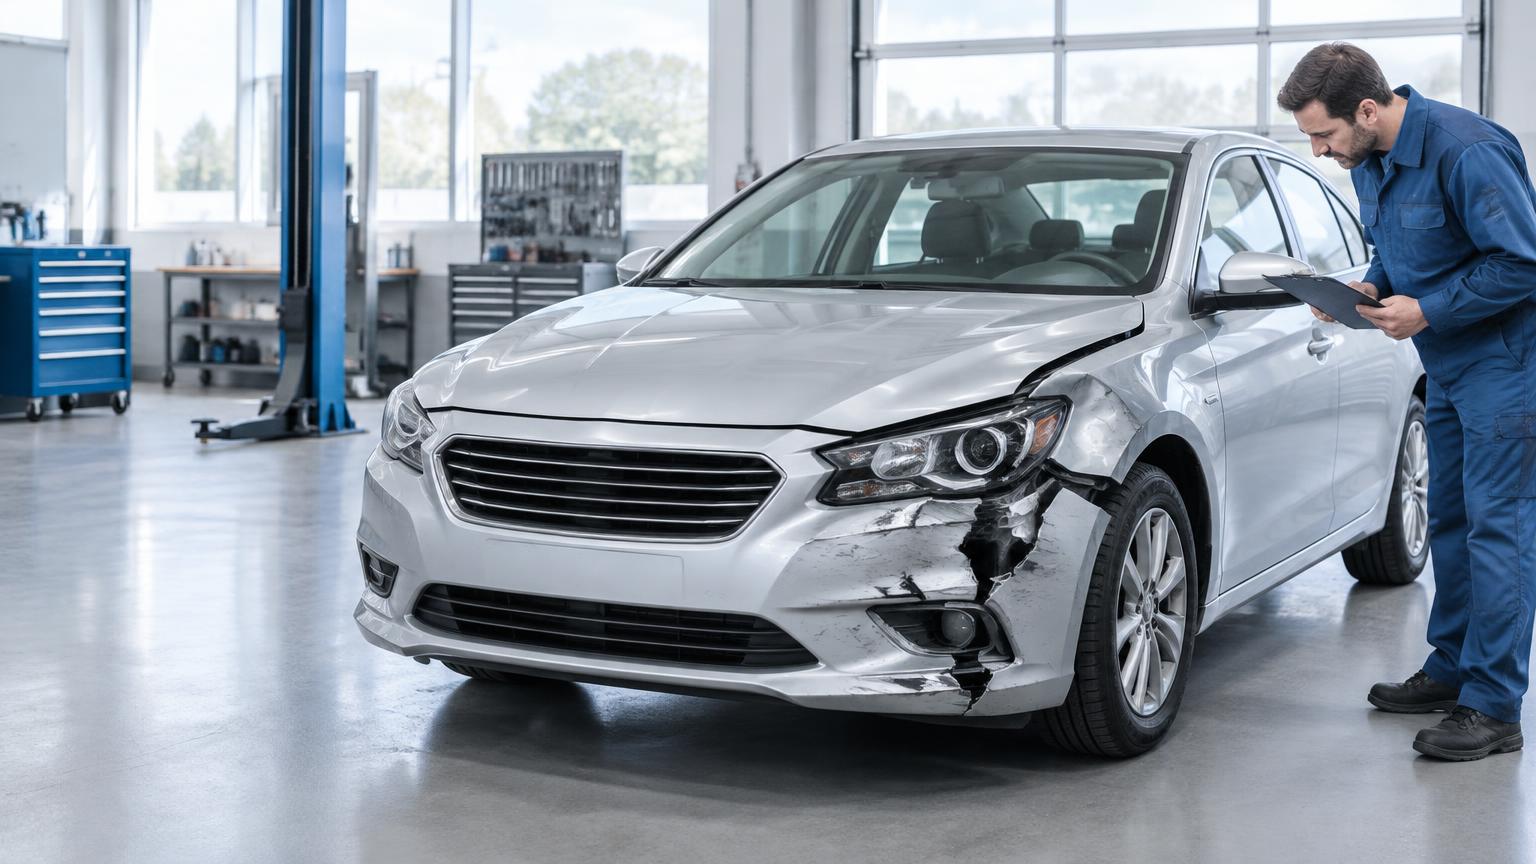
An initial estimate may cover only visible damage. Hidden structural damage, wiring and mounting points can emerge after disassembly. A documented supplement helps bring those repair costs into the claim.
PRIMUS · VEHICLE CLAIMS
A proper repair starts with a complete estimate.
Don’t let a low insurance estimate define your vehicle’s repair. We help document the damage, challenge omissions and advocate for the repair your claim supports.
Free initial evaluation · No obligation
Beyond the first estimate
An insurance company’s first repair estimate is a starting point—not necessarily the full cost of restoring your vehicle. Cost-saving parts choices, missing operations and incomplete inspections can leave a gap between the offer and a properly supported repair.
An initial estimate may cover only visible damage. Hidden structural damage, wiring and mounting points can emerge after disassembly. A documented supplement helps bring those repair costs into the claim.
Insurer allowances may not reflect local repair rates or all required operations. Scans, sensor calibration, corrosion protection and paint blending should be reviewed against manufacturer repair procedures.
An estimate may specify aftermarket, recycled or reconditioned parts to reduce costs. Part fit, material, compatibility and manufacturer requirements matter—not just the lowest price.
The OEM conversation
Original Equipment Manufacturer (OEM) parts are made by or for your vehicle’s manufacturer. They can be important for fit, performance and compliance with manufacturer repair procedures—especially for structural components and safety-related systems.
We compare the estimate with manufacturer guidance, your policy and applicable law, then document why an OEM part or specific repair operation is warranted.
OEM reimbursement is not automatic. Policy endorsements, vehicle age, state requirements and the repair evidence can affect what the carrier must pay. We advocate for supported costs, not promises your coverage cannot meet.
Real claims. Meaningful recoveries.
Behind every settlement is a vehicle owner who deserves a properly supported claim. Client identities remain confidential.
$65,541.66
Recovered settlement
Plus$1,267.30 for personal items left in the vehicle that required replacement.
$16,294.36 above the initial valuation
Challenged AAA’s low initial total loss valuation after an accident and recovered a substantially higher settlement for an anonymous SUV owner.
$5,792.00
Reported total resolution
Secured a resolution after the vehicle owner faced pushback on the repair settlement.
Reported figures are shown as supplied; the component amounts differ from the reported total by $0.47.
Thousands recovered
Across complex vehicle claims
Successfully challenged low insurance payouts, recovering thousands in hidden vehicle market devaluation and underpaid repair costs on complex commercial and passenger vehicle claims.
Past results do not guarantee a similar outcome. Every claim depends on its evidence, coverage and applicable law. Amounts shown in USD.
View success storiesIn your corner
We compare the insurer’s offer, shop estimate, policy and damage photographs to identify gaps and disputed items.
We work with repair documentation and manufacturer procedures to support missing operations, proper parts and justified supplements.
Within our licensed scope and where permitted, we present the supporting evidence and communicate with the carrier about the repair costs your claim supports.
Service availability depends on jurisdiction, licensing and claim circumstances. Educational information only; not legal advice or a guarantee of recovery.
A little clarity
You can ask for an explanation of disputed items and provide supporting repair documentation. A body shop may submit a supplement when additional damage is found. Review settlement terms before accepting a final payment or signing a release.
No. Coverage and legal requirements vary. Manufacturer repair procedures, your policy, OEM endorsements and the specific component can help support a request for original parts.
Your VIN, accident date, insurance policy, claim number, insurer estimate, body shop estimate, damage photos and any settlement paperwork are helpful.
Start with a free evaluation of yourvehicle damage claim. Already a client? Head to your portal.